
 AN INDEPENDENT VOICE OF PUBLIC.
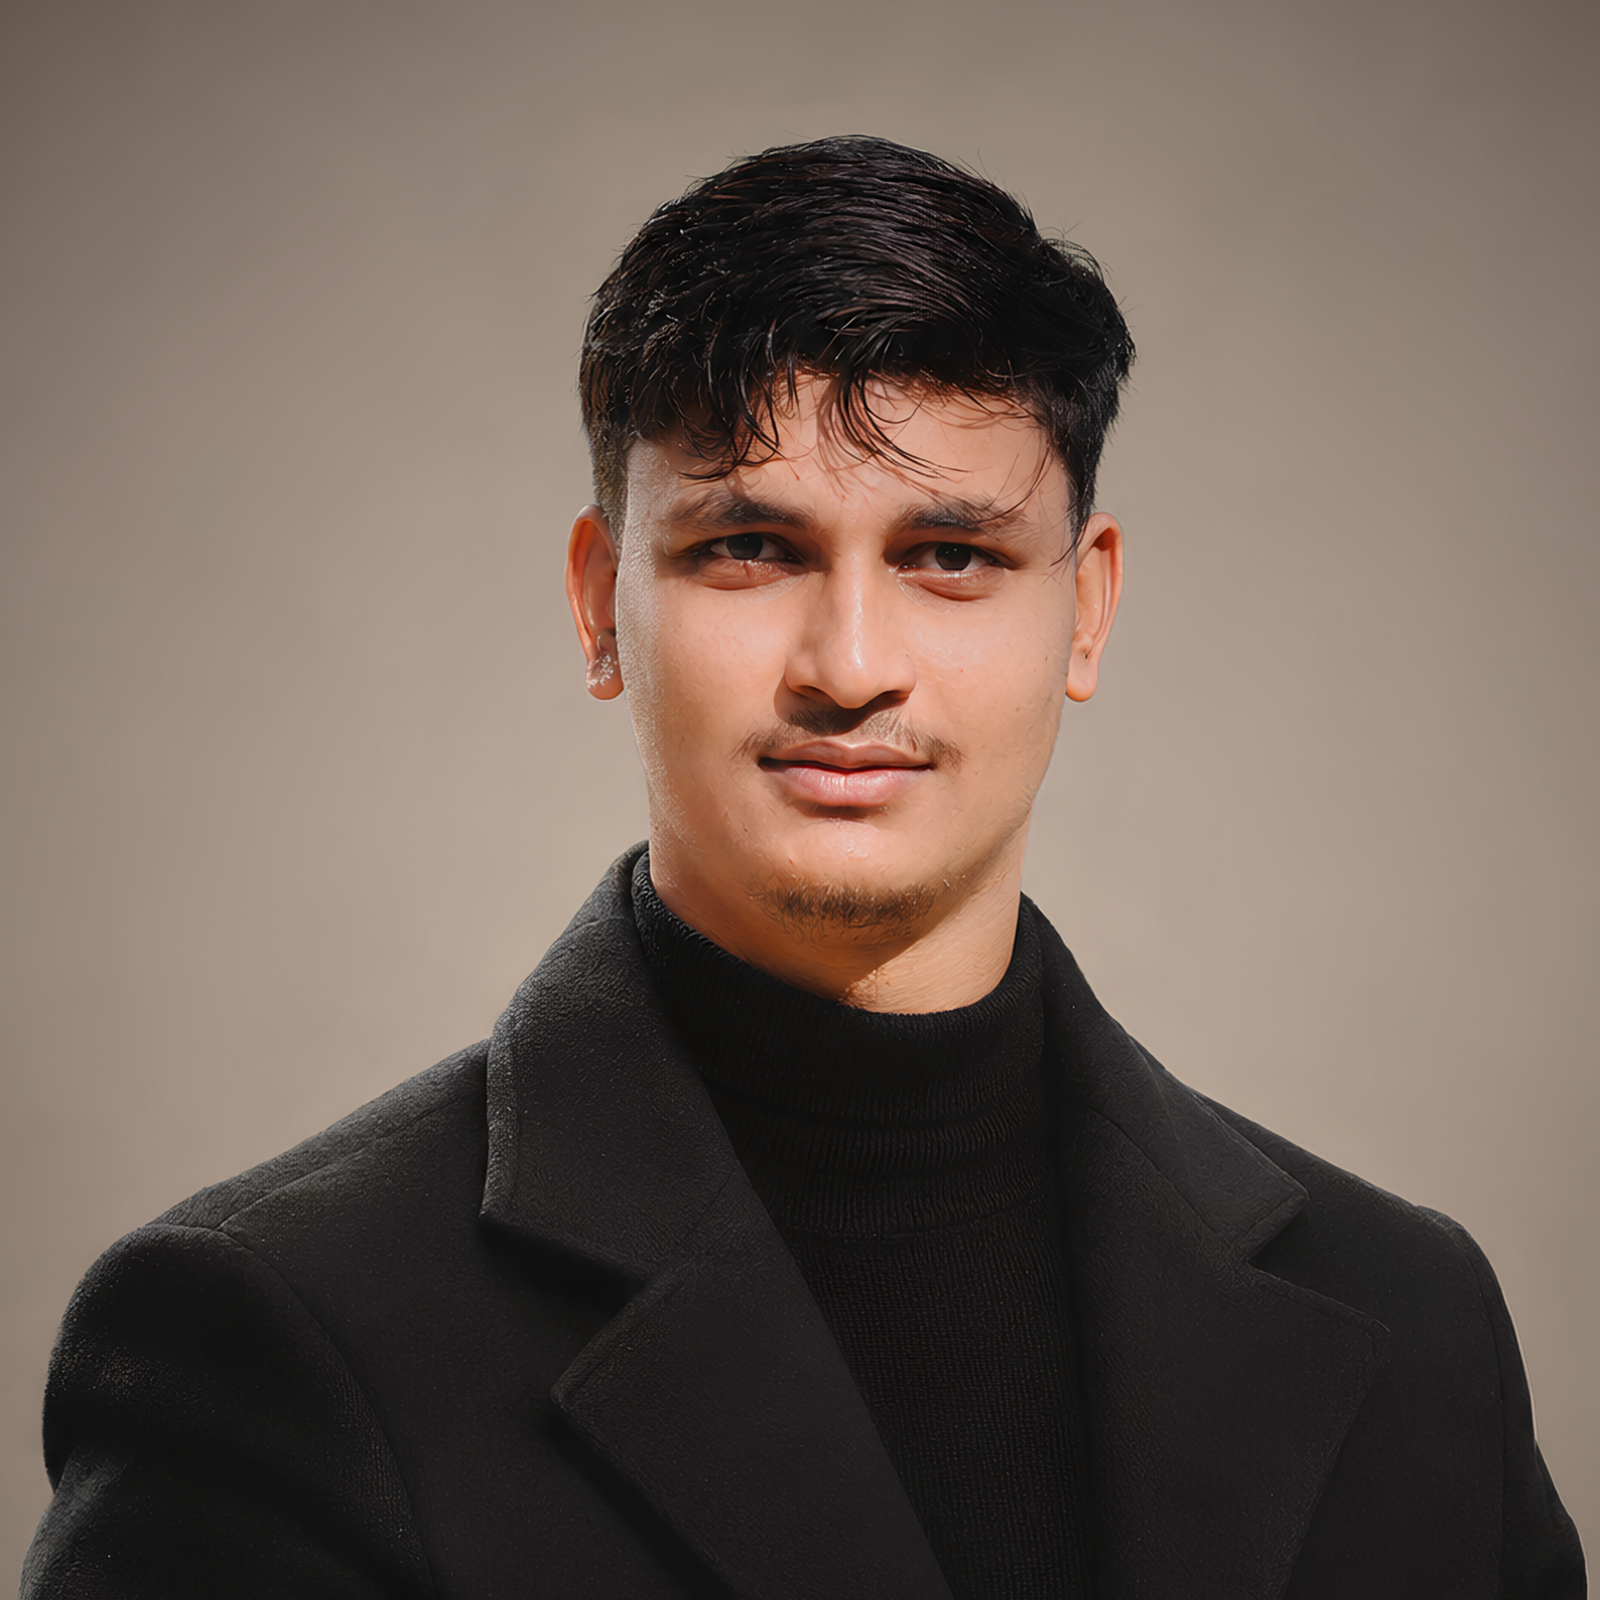

Life insurance products are attracting greater interest from Nepali savers as declining bank fixed deposit rates make traditional savings less attractive, according to Nepal Life Insurance Chief Executive Officer Pravin Raman Parajuli.
Parajuli said the company's current bonus rates range from approximately Rs 56 to Rs 85 per thousand, equivalent to 5.6 to 8.5 percent of the sum assured under the applicable bonus calculation. He argued that even the minimum rate compares favourably with returns available from bank fixed deposits.
Speaking about changing investment preferences in Nepal's financial sector, Parajuli said life insurance savings products offer both financial protection and the potential to receive returns at maturity. He also noted growing interest in single-premium insurance policies, which allow customers to pay the premium in one instalment rather than through regular payments.
Declining Bank Interest Rates Drive Interest in Life Insurance
The reduction in fixed deposit interest rates has encouraged some customers to consider alternatives to conventional bank savings.
According to Parajuli, lower returns on bank deposits have made life insurance savings products more attractive to individuals seeking a combination of financial protection and long-term savings.
He said Nepal Life's bonus rates currently range from Rs 56 to Rs 85 per thousand, with the minimum rate representing 5.6 percent. However, actual policy returns depend on the specific insurance product, policy conditions and applicable bonus declarations.
The comparison should not be interpreted as a guaranteed annual investment return equivalent to a bank deposit interest rate.
Investment Restrictions Challenge Insurance Companies
Parajuli also highlighted the challenges facing life insurance companies as interest rates decline and investment opportunities remain limited.
He explained that insurance companies previously placed as much as 90 percent of their investments in fixed deposits, bonds and debentures issued by banks and financial institutions.
With deposit rates falling, this investment structure has become less effective in generating sufficient returns to meet long-term obligations.
According to him, insurance companies collect funds against policies that can run for 15 to 20 years, but finding suitable long-term investment opportunities remains difficult.
He said Nepal Life had approximately Rs 297 billion in investments during the first quarter of the current fiscal year. Based on the company's estimated 26 percent market share, he placed the broader life insurance industry's investment portfolio at approximately Rs 12 trillion.
Parajuli said expanding investment opportunities in productive sectors, including hydropower, solar energy, tourism and agriculture, could help insurers diversify their portfolios.
Lower Investment Returns Affect Policyholders
The declining returns on investments are also affecting the financial performance of insurance companies.
Parajuli said lower investment income has contributed to reduced bonuses for policyholders and lower dividends for shareholders compared with the previous year.
He explained that approximately 90 percent of the returns generated by an insurance company go to policyholders, while the remaining 10 percent goes to shareholders.
Despite these challenges, he said the life insurance sector had maintained business growth of approximately 20 to 22 percent.
He also reported that Nepal Life had achieved an improved Double A credit rating from ICRA Nepal, compared with its previous Double A minus rating.
Insurance Sector Faces Long-Term Investment Challenges
Parajuli stressed the importance of diversifying investments and creating additional opportunities for insurance companies to invest in long-term projects.
He said the insurance industry needs a stronger investment framework to protect policyholders' funds while maintaining the ability to generate sustainable returns.
He also discussed the importance of spreading insurance risks through reinsurance arrangements, particularly following natural disasters such as the Bhotekoshi floods.
According to Parajuli, claims related to the floods were gradually being submitted. He said reinsurance coverage was expected to limit the direct financial impact on life insurance companies.
He further emphasised that insurance risks should not be concentrated entirely within domestic reinsurance companies and that risk-sharing arrangements should reflect the financial capacity of individual institutions.
The broader challenge for Nepal's insurance industry will be balancing competitive policy returns, long-term financial security and responsible investment management as bank interest rates remain low.


Join the conversation
Comments are reviewed before publication. Your email stays private.